With the Nikkei having now reached and exceeded its previous all-time high, investors are asking what is next for the Japanese market. What does the near- and long-term look like for Japanese equities, and can they sustain life at this elevated altitude?
Highlights:
|
Is it too soon to bet on peace?
On May 25, the Nikkei closed at 65,158.19 yen, up 2.9% from the previous weekend, surpassing the key 65,000-yen level and reaching a new all-time closing high. In the weeks since, the market has continued to rally and now resides above 70,000.
Positive sentiment was partly supported by a weekend Axios report citing a senior U.S. official who said the United States and Iran were close to an agreement that included a 60-day ceasefire extension. Buying, led by richly valued semiconductor stocks, pushed the Nikkei higher that day.
In considering the outlook for the market going forward, careful assessment of the still-unpredictable Middle East situation remains necessary. We have previously commented on the profound uncertainty this conflict has unleashed, and cautioned against investors jumping to conclusions too hostility which might prove false as new information appears.
Importantly, despite limited hostilities on May 26–27, the market appears to view these as exceptions rather than a return to full conflict. With U.S. midterm elections in November and Iran’s domestic economy under strain, ending the conflict may be a realistic option for both countries. This view seems to be spreading in the stock market, and unless U.S.–Iran fighting resumes or escalates, we believe the market has moved past the stage where delays in reaching an agreement would trigger sharp declines.
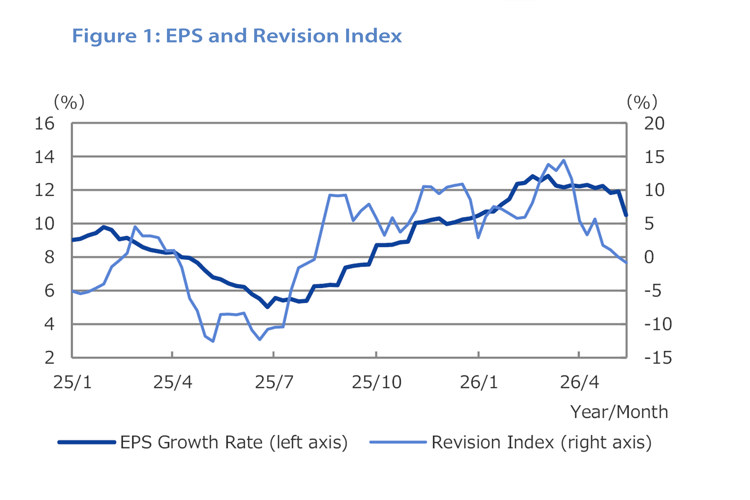
Source: Prepared by Sumitomo Mitsui DS Asset Management based on data from Datastream.
Going forward, if the U.S. and Iran reach a deal to end the fighting, upward revisions in market forecasts are highly likely. As soon as expectations grow for improved company guidance, we expect to see the rally strengthen.
This expectation that the rally will in all likelihood have further to run has led some analysts to caution that signs of overheating may appear.
However, across the broader Japanese market valuations remain moderate and we see this as a stabilising factor moderating the rally. For instance, the 12-month forward price-to-earnings ratio for the TOPIX stands at just 16.5, compared with 21.1 for the S&P 500 and 26.2 for the Nasdaq Composite. Whilst Japan has tended to trade at a discount relative to the US, this gap does mean investors in Japan have less to fear as Japanese stocks are not ‘priced for perfection’ as they are in the US.
As we have discussed before, Japan is relatively well endowed with industrially competitive companies in various market niches, and these firms are now strong candidates to go ahead and grow their earnings well when a full settlement of the Middle east crisis is reached.
What comes after 70,000 for the Nikkei?
From here, we see the Nikkei staying range-bound near its current level or dipping to around 68,100 by year-end in our core scenario, with the upper end of the forecast range for each quarter reaching up to 74,900 yen. In addition, the upper end of each quarterly forecast range is set above 70,000 yen.
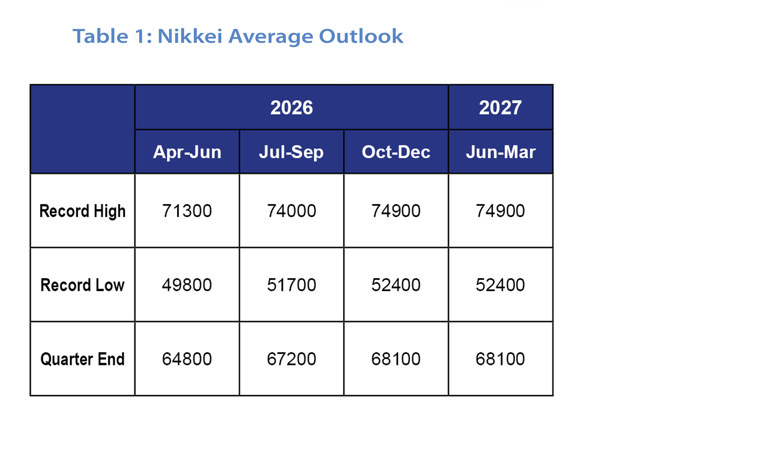
Source: Prepared by Sumitomo Mitsui DS Asset Management.
In addition, the upper end of each quarterly forecast range is set above 70,000 yen. If the Nikkei firmly establishes itself in the 65,000-yen range and Middle East tensions ease, a move toward 70,000 yen within the year may become more clearly defined.
In Japan, amid expected underlying inflation, the average wage increase in the 2026 spring labour negotiations exceeded 5% for a third straight year, and efforts to improve corporate capital efficiency continue.
Furthermore, if revisions to the Corporate Governance Code this year encourage companies to use cash and deposits more actively for growth investment, improvements in ROE can also be expected. If the Basic Policy on Economic and Fiscal Management and Reform, due in June, further boosts expectations for growth investment, the environment for stock prices is likely to become even more favourable.
Oskar Alexander POTYKA, CFA
Director of Business Development
MARKETING COMMUNICATION FOR PROFESSIONAL INVESTORS ONLY – 10/03/2026
General This is a marketing communication. Please refer to the prospectus of SMD-AM UCITS Fund (the “Fund”), and the Key Information Document (“KID”) for the relevant sub-fund before making any final investment decision. Investors should also take into account all of the relevant sub-fund’s characteristics and objectives as described in the prospectus and other fund documentation before investing. Financial information on the Fund is provided in the latest audited annual report or interim, whichever is newest. The KID, the prospectus, the articles of incorporation and the most recent annual report and the latest semi-annual report, if published thereafter, are the only binding basis for the purchase of shares and investment decisions should be based solely on this. These documents can be obtained free of charge at Sumitomo Mitsui DS Asset Management (Deutschland) GmbH, and on https://www.smd-am.co.uk/fund-centre. The prospectus of the Fund is available in English and the KID is available in the official language of the countries in which the Fund is available for distribution. Please note that the prospectus is not available in French. This marketing communication is provided to you by Sumitomo Mitsui DS Asset Management (Deutschland) GmbH. Sumitomo Mitsui DS Asset Management (Deutschland) GmbH is a limited liability company incorporated in Germany under the company registration number HRB 141563, with registered office at Neue Mainzer Straße 52-58, 60311 Frankfurt am Main, Germany. For the avoidance of doubt, Sumitomo Mitsui DS Asset Management (Deutschland) GmbH acts exclusively for the account and under the liability of AHP Capital Management GmbH and is not itself authorised as an investment firm within the meaning given to this term by Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (recast) (“MiFID II”). This marketing communication and any information contained herein is exclusively intended for use by and directed at individuals who are “professional clients” within the meaning given to this term by MiFID II. No Offer; no Invitation to Buy - This marketing communication does not constitute advice, or a personal recommendation to buy, sell, hold or otherwise transact in the Fund, securities or other specific investment products. The prices and valuations shown are non-binding and, like other included information, are for informative purposes only. You should read the KID, the prospectus and the last half / annual report and contact a professional adviser for personalised advice before making any investment decision. No Investment Advice; No Investment Recommendation or Investment Strategy Recommendation -The information contained in this marketing communication does not represent investment advice within the meaning of Article 4(1) (4) MiFID II or any other recommendation to buy securities or products within the meaning of Article 3(1)(34) of Regulation (EU) No 596/2014 or investment recommendations within the meaning of Article 3(1)(35) of Regulation (EU) No 596/2014. Risk Warning - You should be aware that there are significant risks associated with the Fund. The complete information on the Funds or respective sub-fund’s risks can be found in the prospectus and the KID, which are available as described above. An investment should not be contemplated until the risks are fully considered. You are reminded that past performance should not be seen as an indication or a guarantee to future performance, and no representation or warranty, express or implied, is made regarding future performance. Investment in any financial instrument and/or designated investment involves risks, including the potential loss of the entire amount you have invested. Investor Rights - A summary of investor rights is available free of charge in English at the following link: https://www.vistra.com/sites/default/files/2024-05/summary-of-investor-rights-luxembourg-klmc.pdf. The management company of the Fund may decide to terminate the arrangements made for the marketing of the respective sub-fund in any jurisdiction. Additional Information for US Citizens - For the avoidance of doubt, the information contained in this document and the Fund presented herein are not intended for distribution in the United States of America or to US persons (i. e. individuals that are either citizens or residents of the United States of America and / or are subject to US taxation as well as partnerships or corporations that have been incorporated under the laws of the USA, a US State, US territory or US possession). Shares in the Fund are therefore neither offered nor sold in the United States of America or to or on the account of US persons. Any subsequent transfer of investment fund units into the United States of America or to US persons is not permitted. Sustainability Related Disclosures - The sub-funds of the Fund are making the following disclosures under Regulation (EU) 2019/2088 (Sustainable Finance Disclosure Regulation - “SFDR”): Detailed sustainability-related disclosures for the Fund, as required by SFDR, are available for all Sub-Funds at www.smd-am.co.uk/sustainability/. Investors should note that, relative to the expectations of the Autorité des Marchés Financiers in France, the Fund presents disproportionate communication on the consideration of non-financial criteria in its management. Management Company: Paying Agents: Contact Details Sumitomo Mitsui DS Asset Management (Deutschland) GmbH |

 United Kingdom
 Switzerland
 Luxembourg
 Germany
 Finland
 Ireland
 Netherlands
 Rest of EEA
 Middle East
 Japan 日本
 Hong Kong 香港
 Singapore 新加坡
 USA
 Other